So Lake Ontario is now to be called Lake America and so a wag has said Canada Geese are also now called Donald Ducks… oh well, let’s await developments there… the loyalists fought-back against the American invaders in the 1812 war and won and the White House was burned-down in 1814. Let’s trust they can be friends again and enjoying one another’s trade on fair terms.
Job vacancies here are at a five-year low as the impact of dramatically increased costs to employers continues to be felt. The other fact is that those in work need to be more careful – the cost savings to an employer of dropping one employee rise the greater the cost of the job and it makes it more likely that redundancy or simple shrinkage will keep happening as the ‘job’ itself becomes financially unviable.
It has now been said that just as we have taxes (and increasing them afterwards) to deter activities – like smoking and alcohol consumption, increasing taxes on jobs is deterring people from working and bosses from creating jobs in the first place. A workless existence is not a positive place for the vast majority of people – let alone the financial independence and pride it should bring. Proverbs 18v9 and 1 Timothy 5v8…
Meanwhile the hypocrisy of politicians continues; there’s never any excuse but when it is overt socialists with snouts in troughs, in theory we feel angrier as they have been elected on the premise they portray of being more mindful of the needs of those at the bottom of the tree perhaps.
So the Scottish leader justifies expensive flights to the US and the World Cup for him and his ‘team’ and Angela Rayner, avowed petitioner and attacker of others against two-jobs’ MPs, earns a hefty sum from speaking engagements – is their skin never too thick I wonder… even the Guardian is turning against Labour MPs who have been ‘at it’ in accepting hundreds of thousands of freebies and beyond ‘representing government’:- MPs ‘failing to learn lesson’ over freebies after accepting £400,000 of hospitality
This suggests the Party hasn’t learnt anything from Sir Keir’s excesses as soon as he hit Office (and before). Of course other politicians are in the fray too but it is the overt hypocrisy of Labour and the SNP which rankles most at present.
Then as an aside, the ‘liberal’ Liberal Democrat Party has admitted religious persecution which led to the removal of a Christian candidate, as he shouldn’t have had overt Christian views. Being told the Party was secular and there was no room for Christianity has led to a lawsuit where it is now just down to the amount of compensation the Court decides to award to the ejected candidate. To think that past strongholds like the West Country saw the Party’s core in deep-rooted Christianity in non-conformist churches and the Christian Temperance movement – how it has deteriorated since. Accepting ‘everything’ and anyone’s rights to practice or enjoy such things without fear of affrontery (unless you disagree with it and another’s free speech which you happen not to like) is not how liberalism was meant to work…
Can I have a second ‘meanwhile’?… The Adam Smith Institute publishes research showing that the numbers of liquid millionaires in the Country have fallen to the lowest since 2008 at 442,000. You might scream ‘so, good’ as it helps wealth equality… though as a few shrewd politicians have said, you never make anyone richer by making others poorer…
It takes 49 average taxpayers to pay as much tax as every millionaire who leaves, so perhaps replace your ‘envy’ for some common sense, politicians! As the National Debt is just about to breach a horrendous £3trillion (despite record Income Tax and Inheritance Tax receipts but because of exorbitant spending on welfare, pensions and public services effectively), we need all the millionaires we can attract – not deter and eject them through naïve socialist equality objectives making everyone poorer. The US situation is not much better – with $40trillion (£30trillion).
Bonds and annuities
So on 1 September, government bonds here and in the US saw new lows, figures not seen for many, many years with UK 10-year Gilt yields the highest for 18 years now and the highest of all the G7 countries. Readers cannot say they are surprised, as we have been flagging this and all those who rushed to buy annuities with their pension funds must be ruing the day as whatever they fixed, is fixed at permanently low rates as terms for new buyers improve the higher the interest rates on government debt go.
The backdrop is not helpful – ostensibly inflationary worries (which also impact the real value of that fixed annuity you may have bought) but we have to hope it is temporary and not heralding interest rates like we had for too many years. Chancellors are not happy as the cost of government debt increases and that needs funding – paying the price of past excesses in reality (though it can be argued that it also stimulated economic growth from which Society has benefited – including the tax coffers).
As ever though it is when it is ‘too much’. If investors globally lose faith and stop buying bonds because they are worried about the Country’s economics, the rates will have to rise even further to attract them back. Bring back Liz Truss… the rates then were far lower contrary to what Labour still suggests! What’s worse for us and a reflection of the present government alone, is that the rates we have to pay are way above countries even like Spain, Italy, Greece and the Czech Republic – that’s saying something, isn’t it. That is the markets’ poor take from Mr Burnham’s first parliamentary speech too – it bodes badly.
Finally, watch out on your mortgage as these signal increases on all types, so if you have a renewal over the next few years, recognise the cost is likely to rocket and with a soft property market too, selling may not be an easy option to clear your excessive liabilities.
How exposed to the US Dollar are you?
We are in the 10% of Portfolio options which are not ‘heavily exposed’ to US Dollar risk according to Defaqto’s latest analysis of the ‘sector’. I suggest that for most investors with most advisers out there, they are in the other 90%. You might say ‘so what?’ or you may care to reflect that currency movements will impact your investment returns. Indeed, since September 2022, the Dollar has fallen (or the Pound risen) by 20%, so the translation cost of your US shares has dropped accordingly. Yes, over 90% of such portfolios are not hedged against Dollar movements and have lots of their assets linked to that.
I think the thing is, how many investors, let alone advisers, are even aware of this and thus recognise it may be a factor in their investment considerations, especially with the political and international situation, rising inflation there, rising interest rates, its National Debt and international investors’ reductions in their holdings of US Treasuries?
The ‘good news’ of a weaker Dollar is that most commodities are priced in them. That said, there has been a significant increase in many commodities from softs to metals so watch-out how this may feed-through to inflation too. Things like sugar, cocoa, cotton and wheat are not alone.
Good news/bad news
At last some good news for Vistry – the shares up 16% as £350million is awarded to it by the Government’s new social homes’ funding. That’s 40% above the recent low point. As the most shorted UK stock, that will have hit the short sellers hard. Halfords announces a strong summer too and the shares continue their ascent – doubling since April. It all helps!
In 2022, McBride, a rather dull household products’ company, saw its shares fall to 16p. On news of a supplier agreements, they rose to £2.06. We have been trimming and they are non-model for new clients now but can we complain? That one-day gain still added over £400,000 to client funds but sorry if you don’t have them. The opportunities are out there – and we would have said ‘all along’ on this one, without the risk the main US market represents now.
Knee-jerk reactions
A survey by M&G found that 81% of investors felt that having a trusted adviser like us saved them from knee-jerk reactions when markets were volatile. It found that 91% of those interviewed said having such an adviser makes their investment journey calmer and more manageable. We have said indeed that how valuable can our service prove to be when things are difficult?
We also escalate communications with clients to share our views on what is happening – as well as taking action as we see it fit at the time. If that ‘saves’ a client doing absolutely the wrong thing, at the wrong time, how does the Regulator expect us to reflect that significant financial benefit to the client in the annual costs levied I wonder…
Online portfolio access
Is online access to your investment valuations imperative? We say ‘no’. That’s not to be patronising either but if a client wants a valuation, we are only too pleased to provide it.
Did you know that Henrys (‘high earners, not rich yet’) check their values an average of once a week with 16% checking daily? It’s not healthy. This is according to a recent Barclays’ survey. Indeed, we have had investors join us because their old firm gave them daily access and during downturns they felt it was their obligation to keep checking and it wasn’t doing their health or sleeping patterns any good.
Oh yes, of course we love to see things going up every day, don’t we all… when clients entrust us with their finances, we are the ones to worry about the daily values and what’s happening in the world and fair enough, if they have discharged that onerous obligation and responsibility upon us, so be it – we have broad shoulders. We’ll do our absolute best – our guarantee – and using all the wiles and guiles alongside our experience and qualifications to help – and a disciplined approach to how we look after all our clients’ funds however and wherever they may be deployed.
St James’s Place (again)
We do come across this firm quite regularly and it has tidied its act dramatically but investors don’t seem to realise that their charges are pretty steep. They are not independent but say that a ‘curated choice of hand-picked, vetted managers protects clients from market noise and decision fatigue’ (what? Is that another way of saying ‘restricted and tied to a limited range of products and managers?), that they will want you to move all you have to SJP products (even if what you have may be great and regardless of the costs which may be involved – we have a new client quoting a 4.5% fee to him to do just that – ours is ZERO) and charge you an annualised review fee. The representatives are paid an initial ‘commission’ out of this from the money invested and a part of the review fees on top.
The Firm was rapped over the knuckles firmly by the Regulator for failing to provide an annualised service to all its customers, despite charging for it. It relented and said it would launch a full review and refund customers who had not had the service they had been promised and for which they were paying a chunky annual fee.
However, despite that, recently a customer complained and SJP tried its hardest to reject the complaint which in the end went to the Ombudsman. SJP tried to say the lady should have known she had not had the service and should have complained at the time, so she was time-barred… the Ombudsman disagreed and demanded that SJP paid compensation. The FCA may be interested to revisit what redress arrangements SJP put in place following its castigation as surely, such a case should have been included? However, that’s not my worry, fortunately but what is it that people see in SJP’s offering which so appeals to them? Slick marketing is one thing…
Premium Bonds
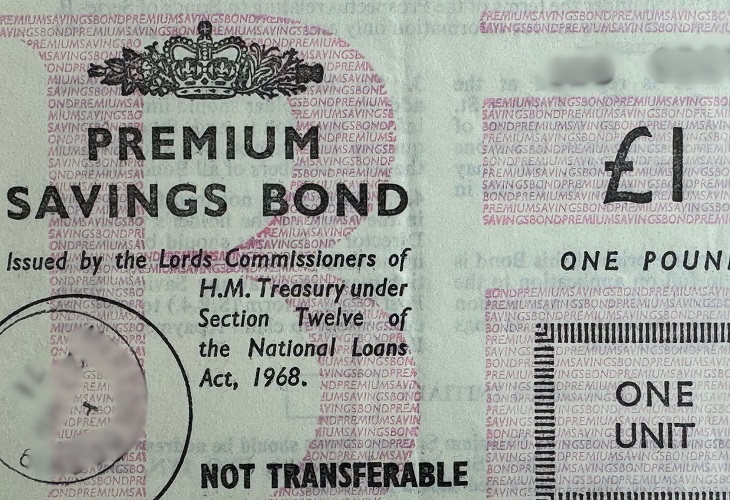 So from September the prize kitty is 4.35%, a little more meaningful but is it enough to entice savers from doing better things with their money then, after a few years resenting not having won much (of course – the law of averages…!). Deduct say 1% for the big ones which aren’t going to you (same law of averages on the reader numbers here!) and I suppose as part of your ‘emergency cash’ it’s not too bad as long as you don’t become superstitious about encashing them when you need funds, nowadays with relatively easy access.
However, don’t forget, your Bonds aren’t in the Draw immediately – a con if you ask me and one which should be reflected in the prize draw percentages for buyers’ information!
My best wishes
Philip J Milton DipFS CFPCM Chartered MCSI FPFS FCIB
Chartered Wealth Manager
Fellow Of The Personal Finance Society, Fellow Of The Chartered Institute Of Bankers