So, diesel and petrol (and heating oil) prices have been rocketing, with the former being the highest it has ever been. Curiously, political pundits pay little heed to the amounts of tax inclusive within the prices we pay, all the way from production to refining and the levies, before VAT is added.
They don’t also say how little refining capacity we have in this Country (or none) and indeed storage for gas, etc and the fact that we are beholden to other nations for our imports, despite having our own fossil fuel resources under our feet and under our shores.
Higher prices for these base commodities, even within a ‘transitioning’ period towards ‘alternative’ fuel sources and greater electrification, will drive-up prices which means higher inflation and even greater pressures on consumers and businesses. The Country’s naivety about failing to protect us better in these vital resources is frightening – let alone concerns for general ‘security’ of the supplies at all. Contrary to what too many like to say conveniently too but the Iran war and ‘Donald Trump’ aren’t the only factor in the equation and there are many issues over which we need to have better control.
Hire Purchase company Klarna has seen its shares droop from a launch price of $46 last September on its flotation to under $13. I have been suspicious of this since the concept started; encouraging people to buy ‘everything’ in instalments and seemingly without ‘any’ regulatory narrative is not healthy. When I hear that people are buying their lunch sandwiches by future instalments I know something has gone terribly wrong – both with ‘what on earth are those people doing’ to ‘what on earth regulatory system allowed that (or didn’t ban it) in the first place.’
This targets naïve and vulnerable consumers (who are the ones meant to be protected by the rules) and the bad debt provisions Klarna is making are testament to that. Frankly, it is a cheat on the Consumer Credit laws and should be banned. Vendors should not be able to circumvent the rules to make credit so easily available and without any background checks whatsoever, effectively. If personally I wanted to lend someone £10 as a ‘business’ transaction and for whatever genuine purpose, the law bans that, effectively, unless we satisfied all suitable (and onerous) regulation and gave protections to consumers too.
Markets
The markets aren’t sure which way to look but as bond rates keep rising, the IMF reminds leading countries that overall national debts are the highest against economic outputs since WW2 and that debt needs cutting, global stockmarkets (well the US) keep climbing the ‘wall of worry’. US Tech share prices remain as spaceward as the hopes for SpaceX on its floatation.
However, there remains compelling value in so many other arenas, regardless of the backdrop and especially in the UK. We should not be surprised to see a little upset as of course, the latest quarterly valuation reports are due as at 5 October so whilst it is sheer superstition, it is amazing how values seem to drift back just as they are due to be produced. Still, by the time they arrive with clients, everything can be very different again – it’s simply one day’s snapshot, after all. We must not forget either that October is a nasty month for markets when crashes are concerned but then, don’t overlook all the other months too… (September is apparently the poorest performing month, historically).
Residential property as an investment
As if things aren’t bad enough already for the residential property market and private landlords with an extra 2% Income Tax on rents from next year and excessive tenants’ rights, the latest part of Labour’s new law will drive far more landlords out of the market and tenants on the streets. I shan’t blame them. There’s an annual registration fee per property of £65 and reports of the properties, rents charged and so on and all certifications will be sought too.
It is oppressive and at the end of the day, it will have to be tenants who pay. And bizarrely, agents can’t do the registrations etc for the landlord. Woe betides if you don’t satisfy the rules too, with serious financial penalties. Is all this really a boon for tenants…?
Sign of the times?
A few years ago, HSBC attracted lots of financial advisers to join it and with lucrative packages. Now it has decided AI will replace up to 70% of its advisory staff… and it plans to deliver more ‘digitally-enabled products’. That has to be worrying both for the industry’s millions of workers but also for the customers themselves…? What career paths will this style of behaviour impact?
Triple or double lock?
A commendation to Mr Burnham for facing the issue bravely but whether what he suggests will make a great deal of difference to welfare spending, I am not convinced. It’s not whether the ‘amount’ is right, fair or anything but just that significant increases are unaffordable by the State in reality, that’s all and there is always the Pension Credit for those at the real bottom. I wonder how the public and then the electorate will treat him… a real problem (and deceit perhaps?) is that a possible arbitrary £600million annual saving is suggested but that doesn’t cover the £40billion of annual costs for the proposed ‘New Service’ and that is before the unions no doubt demand dramatically increased pay rates for their newly recognised, financially flush service…
Millionaires
It’s not an invitation (and I shouldn’t want to live there anyway) but for all those who say high-tax authorities like ours don’t drive millionaires away nor do they attract new talent and wealth to their countries, the principality of Monaco has a mere 39,000 people with an average wealth of $20million (a third of the population being a millionaire). It is not in the EU nor constrained by the EU and its diktats either. Figures published in November show its economy grew by 8.8% in the year.
As shared before, conversely the numbers of millionaires in the UK have fallen to their lowest level since 2008 according to the Adam Smith Institute and the rest of us have to pay more tax as a consequence.
Company initiatives
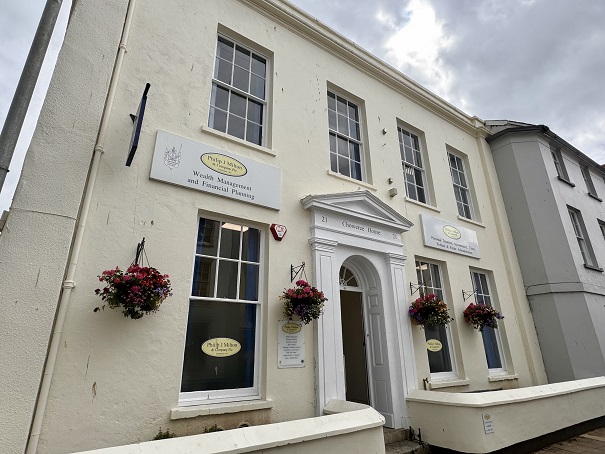
From 1 October we cut the maximum brokerage charge on transactions in portfolios by half. Whilst this reflects economies of scale we are pleased to be able to pass on to clients, we do look meaningfully at all charges constantly, to see if there are any ways we can make them even more economic but the cost of ‘regulation’ generally is pressing constantly against that. We shall keep trying! I should remind clients that there are no minimum brokerage charges nor management fees so for smaller transactions and accounts they are remarkably tiny!
As a staff perk too, as well as helping to train and encourage them to see how the markets work, we are introducing an ‘Investment Club’ as a perk both to help them generate returns from investing collectively but also to learn how they may be able to benefit themselves with their finances. The Company will underwrite the first £250 of losses too, not that we want any losses but to help ensure anyone can join! We are unaware of any other firm which offers such facility? We wish all joiners well and we have seeded the Club with some silent money on equal terms and to give them the returns on that too!
Good news/bad news
Builders like Vistry jumped on the Government’s announcement to encourage first-time buyers with loans for deposits etc but since slumped almost immediately. Alongside AIM stock Michelmersh, our recent Ibstock purchase has proven fortuitous – it makes bricks and they jumped even more.
Saga jumped 23% on more promising results – still ‘jam tomorrow’ and a long saga for those loyal people who bought at the float in 2014, as they sank significantly during covid. We started buying in strategies too soon but chased them to the bottom in October 2022 when they were 74.5p. They have now become a ‘ten-bagger’ and even rising over threefold since the start of 2026. We are going to struggle to duplicate some of these astonishing results attained from the select few direct stocks we hold… this single move on one day added £660,000 to clients’ funds – or put another way, 0.2% of the total we manage; all these sums become meaningful over a year! Then the same day, Liontrust announces the purchase of Hawksmoor and the shares rally 18% so it all helps!
Of course it is never all good news; Tullow Oil has a bad tribunal outcome and the shares drop by 47% but at least they are and always were a ‘fringe’ investment compared to the larger holdings of more mainstream assets we hold. Pennon – owner of South West Water – slumps a fifth on coming to the market to raise yet more capital as well as signalling reduced dividends – not a positive sign. The Rights Issue is deeply discounted but cheap at these levels. So much for shareholders winning on privatised water companies… the shares are the lowest they have been for over two decades.
Schroder Global Innovations Trust tendered for redemptions and we are pleased to announce that almost 20million of our shares received the price of 22.29p and no brokerage. At the time of writing, the price on the market is 15.6p so shareholders have received a special bonus of 43% on the price at which they can buy a share today. We are continuing to add shares. Remember, these sorts of bonuses are never received on unitised holdings as most investors hold and are sold (and most advisers or managers promote). They are not assured but whenever we receive our proportionate share of the underlying assets in the pot, if we have bought shares at a discount then we receive a very acceptable bonus – and all for nothing.
Watch(es) out!
Here’s an off-the-wall. Are luxury watches going to go on the out? Their marketing has been fantastically successful, encouraging people to spend significant money on them. Yes, often they include silver and gold etc, to add to the allure and to make them collectable (though they do need servicing and certification to preserve their value, all extra revenue for the manufacturer and agents). The antique concept behind them and their amazing technology and creation help with the illusion but will the interest fall-away over time? Yes, already they do fall in value and not just rise but as the progression of ‘tech’ timepieces linked also to your health monitoring take precedence, where will people wear their glamourous timepieces in the future?
I enjoyed a piece in the Daily Telegraph recently about high-end dining room tables which have plummeted in price as basically fewer and fewer dine together as opposed to in front of the TV. Even high-end, best quality antique dining tables have fallen by as much as 90% as they are just not sought-after as they used to be. Is this the fate of glamourous watches? If so, you heard it here first and no, I don’t have one and have never coveted one! What will those who wish to show-off some symbol of affluence adorn instead I wonder! And remember… fob watches used to be the necessary item for ‘everyone’! Now, apart from the precious metal value, most are accessible for hardly nothing.
Client interest
Lawyers are up in arms as the Government has suggested that all interest they keep on client funds will have to go straight to the Treasury, a figure suggested as £100million each year. To be frank I am astonished that the interest is not paid to clients, without deduction, as it is clients’ assets – not the lawyer’s and nor the Taxman’s. Just imagine if we kept our clients’ returns!
How come this ‘loophole’ exists at all – clients’ securities and the returns from them are sacrosanct; we can’t mix clients’ and our own funds and any sense of exploiting clients like this would be punishable with severe repercussions. All temporarily held funds in our general Client Accounts have to be monitored for possible interest payments to clients too. All that said, some firms do keep a proportion of some payments (eg interest) as a result of centralised management and economies of scale but the FCA is even frowning upon those as breaching the ‘Fair Value’ provisions under the Consumer Duty.
I suggest the legal profession should recognise the honourable way out here and start giving their clients the interest on their money and then it won’t go to the Taxman either.
Playing chicken
Courtesy of the FT… every man, woman and child in the world eats 10 whole chickens a year. In 1957 the average chicken was 905gms, doubling by 1978 and in 2005 it had more than quadrupled to 4.2kg (after a mere 56 days). The humble chicken has become the leading meat protein source across the world with mankind’s genetic evolutionary assistance (selective breeding and enhanced food sources, not hormonal input) propelling its usage and its economic value, from poorer to developed markets alike.
My best wishes
Philip J Milton DipFS CFPCM Chartered MCSI FPFS FCIB
Chartered Wealth Manager
Fellow Of The Personal Finance Society, Fellow Of The Chartered Institute Of Bankers