At last the economy grew and better than hoped – by 0.4% in the quarter to 31 July and apparently fuelled by AI efficiencies and World Cup spending. However, the Government really has problems. Ostensibly it has sold the most expensive 30-year debt since 1998 – 5.82%. The very first 30-year started on 28 January that year.
I should add, the first UK Government debt issue was in 1694 but we are well behind the first ever, issued in Venice in 1171.
Remember, that rate was under 1% in 2020! At time of writing, those long-dated gilts have been plumbing new lows again, nudging 6%. The ECB has raised rates again by another 0.25% and across the Atlantic, bond yields there have been creeping inexorably higher too. That said, the UK remains the highest payer in the G7, our debt adjudged as higher risk, under this government.
We watch many things to help us assess markets and expectations going forward. The whole world of financial management and ‘predictions’ is complicated and often forgets the participants are also emotional human beings – even when they are dressed-up as ‘investing institutions’ with big reputations. However, they also ‘go wrong’ sometimes, as the financial graphs of time show.
What is also interesting is ‘how’ the ‘hexperts’ seem so often not to notice ‘things’ changing. One at the moment… no one seems to be giving much attention to the significant price increases in so many commodities, from metals (with copper at all-time highs) to softs, like sugar, cocoa, coffee, wheat, cotton, etc. Yes, plenty of this is a bounce from well over-sold, years-long nadirs but as prices rise, guess what happens… inflationary influences appear as those base price increases have to be passed-thorough to consumers. We have enjoyed a lengthy period where weak commodity prices have been cutting costs (believe it or not but sadly other costs like employment have countered those) but that has turned and it is now a negative.
Listening to the very interesting latest presentation from Temple Bar (not one we own but I admire, watch and we might!) but Mr Nick Purves reminded participants of some common sense on market valuations, specifically the US. All he said was that history has proven (and will prove again, mark my words) that whatever the asset, the higher the valuation base when you buy, then the lower the future returns you will receive. Contrarily, the lower the valuation point at entry, the higher the long-term returns.
Of course it is never ‘black and white’ but it’s that expression called ‘common sense’ I guess, not rocket science but as he also says, this is not a prediction of where the relevant markets will go in the near term. I add-in that the ‘cheaper’ something is when you buy it, then the lower the risks you face too. Of course, that is then up to us how we research and define ‘cheap’ but I suppose I can say, without being arrogant, nor ignoring the ones which went wrong (and there will always be those) but our long-term business success must say something for the approach. We now manage £325million discretionarily for many clients, with recent increases dominated by ‘performance’ as the statistics show but please always remember – it is our views today and how we exercise those judgements now and the future which are most important – not the past:- https://www.miltonpj.net/services/portfolio-benchmark-returns/
Meantime, some more good news for investors in that according to ‘Dividend Watch’, global dividend income increased again and above inflation in the second quarter, rising by 7.9% to a total $827billion.
When green means gullible
Well intentioned investors wanting to ‘save the Planet’ were keen to react to Bournemouth based ‘Ethical Forestry Ltd’s investment scheme of planting trees in Costa Rica, a scheme which would generate a good return whilst at the same time doing something good for the Planet – ostensibly commendable. However, the three directors behind the Company have now been jailed after £70million disappeared, fuelling extravagant lifestyles for themselves and vast tax avoidance schemes. How many times have we tried to warn investors?
I remember having chats at the time with some investors and it was almost impossible to dissuade them, in the face of the high-pressure sales’ tactics of the commissioned salespeople who didn’t care who they were defrauding or what they said to extract money – lots of it being transfers from mainstream ‘boring’ pension plans. And was it regulated? Of course not – so no protection.
This went on for seven years and despite red flags throughout the industry. Finally the regulatory machine worked but not before it was too late for so many. Pleasingly, this scenario is almost impossible to replicate now as the regulations have become so tight that it has become almost impossible for the honest and upstanding to operate but that’s another story again!
However, there is a lesson here – even regulated schemes backing the latest ‘trendy thing’ can all end in tears for investors – legitimate entities perhaps but where the pedlars of them do best out of the sales – however honourable the cause might be on the surface, from solar farms, to wind energy and hydrogen fuel companies, let alone AI and space technology. Just please be careful out there – or use a reputable adviser not swayed by the latest temporary breezes (or even permanent and fantastic ones being sold too expensively!)
Insurers
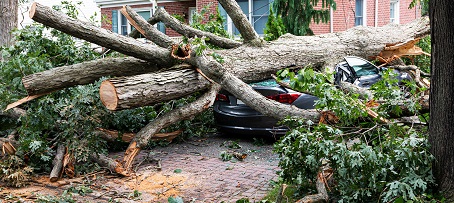
Incidentally and whilst open debate is imperative about the subject (despite the narrative) and how we react and not over-react (and not said as a comment to challenge or fail to recognise that human beings have an impact on our world) but to befuddle the extremists, the Super El Niño has done the exact opposite and is heading for the fewest hurricanes welling-up in the Atlantic since proper records were maintained, back as far as 1939 according to some pundits. Yes, I know there will always be excuses but that is not what they said before and it’s always easy to reinvent the science afterwards to explain why your first science (which we are all told not to question) was, er, ‘wrong’.
However, this is the financial point which so far I have not seen noted anywhere. Fewer hurricanes mean less severe weather (hurricanes and indeed those ‘enjoying’ the tail winds) and guess what, that means less property damage and lives lost. Yes, the significance of that is likely to mean a bumper year for insurance and reinsurance companies, especially after they hiked-up rates in latter years because of the increased claims, the received climate change wisdom and indeed because more people were buying their policies. And yes of course, unusually arid conditions elsewhere can increase subsidence claims but insurers should have provisioned for these – especially after all the ‘science’ has been predicting that for years too.
Now, I can’t say which ones have significant exposures to the relevant pools but there are several which ‘may’ or ‘do’ and where their shares are not expensive anyway so that seems a very attractive thematic investment line before everybody realises.
The ear of the Financial Times
Here is an interesting marketing story. So, I write to the FT (in fact I wrote four letters all told, over a few years, even trying the managing director in Japan) noting that it had some problems with its listing of certain prices in the hard copy Paper, which I still enjoy taking that way as it suits me. I never received a single acknowledgement, despite being a loyal reader for over four decades. However, in time, the Paper reviewed its errors and omissions and corrected the errant data.
Then recently, my last letter noted that certain daily prices in some of its tables were printed on such a dark colour that they were nigh impossible to read. No one there had bothered to proof check but again, after a little while, clearly my letter had arrived and they did something about it – well done and thank you.
What is the lesson? Well, all these feedback surveys that I receive on what I might like about the Paper etc – what point are they if you fail a basic marketing tenet of not recognising your customer, valuing them enough even to send the courtesy of a one-line email of appreciation to the writer taking the time to note an issue which needed addressing?
Are these firms too big to understand the precepts of basic customer service and how that fits in the marketing mix? You can lose lots of customers by simply being too rude or ignorant, even by not answering correspondence or attending to basic enquiries, nightmarish waits on the telephone, countless push button service functions to navigate before you may, if you are fortunate, connect with what or whom you need to speak, no email addresses or telephone numbers on correspondence or published on websites, etc.
Well I know that for our Firm I realised the importance of this many decades ago and indeed I believe that is part of our success – the quality of the service we endeavour to provide. How come the big firms missed that basic lesson – I mean, a simple email of thanks in acknowledgment?
Markets and the price of a share
In theory, a share price is the sentiment between buyers and sellers. The price today reflects the agreement that a buyer is prepared to pay that figure to hold it and a seller is willing to let it go too. ‘Sentiment’ is meant to reflect all the information ‘out there’ at that point – the underlying company’s business, profits, assets, prospects, etc. But yes, this ‘sentiment’ can and will vary like the wind in the short-term and sometimes for much longer too!
Warren Buffett said poignantly that ‘the stock market is a voting machine in the short-term and a weighing machine in the long term’. In other words, today’s prices reflect erratic human emotion (backed by substance in the underlying company too of course) but if more people buy enthusiastically than sell, the price rises and vice versa. Then extremes of excitement – both positive and negative – will have exponential impact on the ‘share price’ from one day to the next and oblivious of the prospects of the underlying company.
Extremes in an individual stock or sector/type of investment will arise because of ‘trends’ or populism, fuelling speculative fervour – and extreme negativity in reverse. We are ‘value investors’ and are much more concentrated on good ‘old-fashioned’ value – when we believe something is fundamentally under-priced compared to its status or prospects.
‘Value’ generally is far lower risk and it pays us chunky income whilst we wait, versus the need for the hyped to become more over-hyped to justify extremely expensive valuations. Yes that can happen of course and it does very often but also it can lead to gigantic bubbles bursting as enthusiasm becomes far too carried-away and then crashes arise – monumental crashes when the sums of money involved are so exaggerated.
There are ways investors can also ‘short’ stocks, so they borrow someone else’s shares and sell them, having to replace later what they have borrowed from a long-term investor later, after having bought them back more cheaply than they first sold. Of the nine biggest shorted UK stocks, we are buyers of seven, as we see fundamental value in very unloved situations there… does that make us right? No, it doesn’t guarantee it but certainly it suggests we have seen value which the market is trying to ignore. We might have to wait a while… but we have learned patience over the decades!
How much return are you losing?
A survey by Murphy Wealth suggests savers will be losing-out over the next decade of a massive £2trillion of combined returns by not investing sensibly and leaving too much money decaying, earning little or nothing on limp deposit accounts. That’s quite a sum – have you ensured your non-emergency cash is sensibly deployed and that doesn’t mean all in Cash ISAs either…?
Interestingly this comes at a time the FCA tells us that over 7million people have more than £10,000 in cash and many of whom will be losing-out on the ‘long-term benefits of investing’. Unfortunately for too long the regulatory system has concentrated too much on the negatives of investing and stopping good outcomes from being provided (especially for those with little and who would benefit the most) – the risks, etc, as opposed to the positives.
It is a little like recognising that there are bad foods out there which can kill you and then emphasising all the bad foods, something which then dissuades people from eating food altogether as there are risks you may eat the bad foods… or transport types which can also kill or maim you so the message is ‘don’t travel anywhere as it may be high risk’. Yes, you’ve recognised the difference – sensible human beings have capacity, when armed with enough information, to recognise they can be informed and make sensible decisions which are not high risk, with their foods and travel, as well as their investing!
On top of that, savers and investors need to recognise that behavioural science says they are prejudiced (note I didn’t say ‘ignorant’ but perhaps uninformed is valid!). Unlocking the realisation that you may be prejudiced irrationally against or for something is the first door to recognising maybe there are better things you can do with your money!
Who’s a poplar feller!
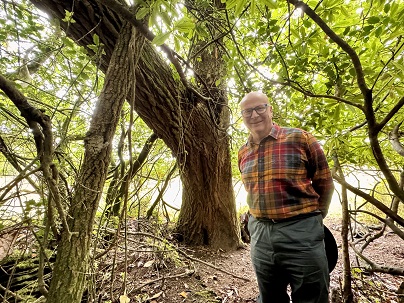
Well actually no, that’s barking up the wrong tree altogether but we didn’t fell this very rare species. For the nature lovers amongst you, enjoy:- Incredibly rare tree gate crashes butterfly open gardens weekend
Good news/bad news
Investment Trust bonus again – Lindsell Train offers to buy-in and cancel 20% of its shares at a 5% discount to the underlying asset value. I suspect we’ll have to take that – after all, the shares are available on the market for a much wider discount than that so an extra bonus for all holders. Thank you. All else being equal, we’ll rebuild our stake at a discount of up to 20% afterwards… and we’ll enjoy a bigger take-up for our holding as many investors won’t tender their stock as we guess they don’t ‘understand’ the nuances.
Associated British Foods, which had been recovering, promptly slumped 10% as it noted a poorer season for Primark. Curiously the price of sugar has rebounded significantly but that has been ignored – it shows that even the larger companies are not insulated from bad news – just to remind everyone! Still, the income is there whilst we remain in the doldrums on this one!
Meantime, energy stocks have reacted positively to the price of oil going above $100 a barrel again. It will be short-term for the underlying commodity but that is inflationary too.
Gold and central banks
As I said before, central banks had been cutting-back on gold purchases because the price has risen and hence also the value of their existing reserves. First quarter 2026 saw the smallest buys for 15 years according to the World Gold Council and less than a quarter of its earlier prediction. They still counted for a third of demand in the second quarter (a much bigger quarter for them again). Some, like Russia, Turkey and Azerbaijan were net sellers.
Overall gold demand in the first half of the year was at 2,522 tonnes, about 2% above 2025. Of course, all these figures must be taken with caution as there is no accord on disclosures of gold buying and holding too! Gold and silver are ‘usually’ a hedge against geopolitical risk but when the price is so high, things stop working the same and short-term too, if interest rates rise then the cost of holding it deters retention, especially if the price has been in descent too, as is the case from earlier peaks in 2026.
Newsletter
We have now been posting newsletters to clients and enquirers for four decades now, continuing despite the exorbitant costs involved with mailing anything physical these days. We believe generally they are well received and typically not ‘selling something’ either but general guidance, ideas, sentiments etc. I suppose too it shows ‘we care’ – which we do.
A recent newer client drops us a note – thank you Dr AS – he says: “I read it from cover to cover – most impressive, with lots of insights, interesting information and useful advice.” Such comments are always appreciated and we are glad that it was helpful. If you are not on the database, please do ask and happily we shall add you – you do not have to be a client to qualify though you may feel compelled afterwards to join our exclusive ‘Club’ as a client, as a result! We shall only guarantee you one thing – that we shall always do our very best we can for you and with your best interests foremost at all times.
It is always very humbling too to receive nice comments from recipients of the eshots – thank you London broker CN who wants a colleague to be added to the list noting it as an ‘excellent newsletter’. We do try!
Regulatory powers – Crispin’ fried
Continuing the FCA’s latest responsibility on for firms but non-financial behaviour unbecoming of a regulated individual will now result in disciplinary action. For Crispin Odey, this means an upheld ban from financial services. Whilst the reasons are manifold and centring upon integrity when dealing with the Regulator and actions requiring investigation within his own firm but ‘odeyous’ behaviour towards women employees, etc was the core issue.
Please excuse the play on words but predatory and bullying behaviour of all forms, whilst never tolerable, now take on a new dimension and Firms have to demonstrate adherence to the requirements imposed upon them to act.
My best wishes
Philip J Milton DipFS CFPCM Chartered MCSI FPFS FCIB
Chartered Wealth Manager
Fellow Of The Personal Finance Society, Fellow Of The Chartered Institute Of Bankers